Costume Sourcing: Working With Vendors on a Studio Budget
Costume costs drive studio profit margins. Multi-vendor strategies, October ordering, resale platforms, and labor markups create sustainable economics.
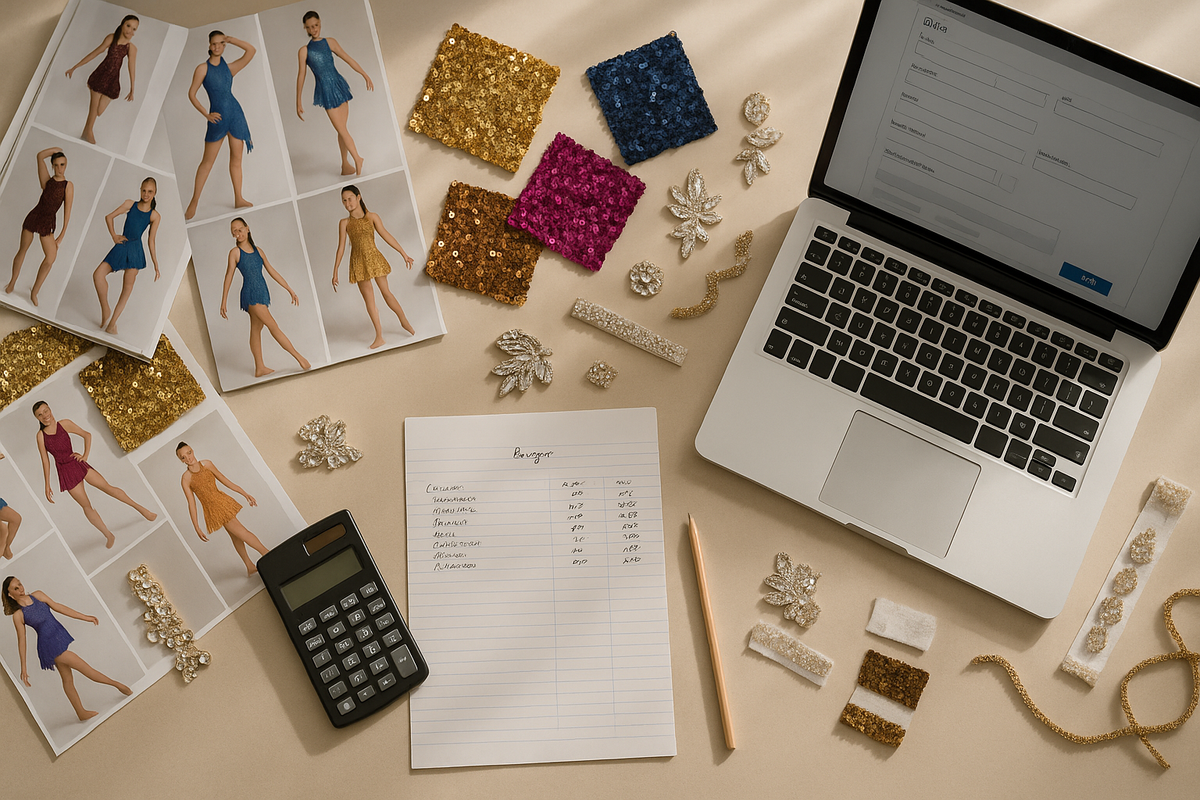
Key Takeaways
- Costume costs directly impact profitability: Many medium-sized studios break even on tuition and rely on costume sales, recital fees, and dancewear markups to generate profit, with typical parent costs of $75 to $100 per recital costume.
- Multi-vendor strategies reduce risk and cost: Using different suppliers for basics, competition pieces, and recital costumes allows studios to leverage volume pricing, specialized design support, and competitive rates across 20+ costume orders.
- Timing determines availability and price: October orders for spring recitals avoid rush fees and size shortages, while off-season buying and annual clearance events offer discounts up to 80 percent off original prices.
- Resale platforms create near-zero net costs: The buy-and-resell cycle enables studios and families to purchase quality secondhand costumes, use them through a season, and resell at comparable prices, particularly for competitive dance routines.
- Hidden labor costs require markup discipline: Measuring, ordering, inspecting, sorting, and managing returns add $25 to $30 per costume in labor expenses that must be factored into pricing strategies.
- Parent involvement and costume doubling lower total spend: Recruiting sewing volunteers, forming costume committees, and reusing one costume across multiple routines demonstrate budget awareness that improves family retention.
The Profit Economics Behind Costume Decisions
Costume sourcing is not a creative decision alone. For studio operators navigating studio operating costs that average over $22,000 monthly, costume revenue represents a critical profit center. Many medium-sized studios break even on tuition and depend on ancillary revenue streams such as costumes, dancewear, and recital fees to achieve sustainable margins.
According to industry benchmarks collected by DSOA, studios typically add $25 to $30 per costume to cover labor related to measurement, sizing, ordering, and alterations. Parents are charged approximately $75 to $100 per recital costume. This markup structure must account for both hard costs and the hidden administrative burden that costume management demands.
Understanding the Major Vendor Landscape
The current costume market is dominated by several established companies, each offering distinct advantages. Top vendors include Weissman, Revolution Dancewear, A Wish Come True, and Costume Gallery, which provide both custom designs and faster catalog options. Custom costumes deliver unique looks aligned with specific choreography, while catalog selections reduce lead times and unit costs.
Studios ordering 20 or more costumes typically qualify for dedicated design support, priority production slots, and volume pricing. Pumpers, one of the largest US providers, offers over 10,000 products and provides fabric swatches for group orders, enabling studios to preview materials before committing to bulk purchases. Operators should contact vendors directly to negotiate studio partnership pricing rather than relying on published catalog rates.
Why Multi-Vendor Strategies Reduce Risk
Many studios use multiple vendors to balance competing priorities: cost efficiency, aesthetic quality, and customization depth. This approach mirrors wholesale sourcing strategies used in equipment procurement, where operators leverage different suppliers for basic inventory versus specialized items.
A multi-vendor model allows studios to assign wholesale suppliers to basics like jazz pants and character shoes, reserve specialty companies for intricate competition costumes, and use resale platforms for cost recovery on gently used pieces. This segmentation mitigates supply chain delays and prevents over-reliance on a single vendor's pricing changes or production capacity constraints.
Timing, Ordering Intelligence, and Seasonal Opportunities
Costume availability and pricing fluctuate predictably throughout the year. Studios should place orders by October for spring recitals to secure full size runs and avoid rush fees. Late orders risk limited inventory, forcing studios to accept substitutions or pay premium expediting charges.
Off-season purchases and annual sales events represent significant savings opportunities. The Dance Costume Liquidation Sale, scheduled for August 23 and 24, offers discounts up to 80 percent off original prices. Studios that plan ahead can stock inventory during these windows and allocate savings toward higher-margin custom pieces for competition teams.
Labor Costs and the Hidden Burden of Costume Management
The visible purchase price represents only part of the total costume cost. Studio owners invest substantial time searching for budget options, measuring students, placing orders, receiving shipments, inspecting for defects, sorting by student, and managing returns for incorrect sizes or colors. Each return incurs replacement costs and additional shipping fees.
This labor-intensive workflow justifies the $25 to $30 markup studios apply to each costume. Operators managing healthy profit margin benchmarks of 15 to 25 percent recognize that underpricing costumes to appear affordable can erode overall profitability, particularly when tuition alone barely covers fixed operating expenses.
Cost-Saving Tactics That Preserve Quality
Several proven strategies reduce costume expenses without compromising the performance aesthetic. Costume doubling, the practice of using one costume across multiple routines in a recital, cuts parent spending visibly. Parents appreciate this approach as evidence that the studio prioritizes affordability.
Parent involvement through costume committees or volunteer sewing can offset labor costs. Some families possess professional sewing skills and willingly alter costumes or source materials. Handmade costumes typically last longer, fit better, and deliver exact creative vision rather than requiring compromises inherent in catalog selections. However, this approach demands clear communication about quality expectations and timelines.
The Resale Market and Buy-and-Resell Economics
The secondhand costume market has matured significantly, driven by competitive dance families managing relentless seasonal costs and studio owners seeking margin relief. The shift toward resale is led by families and studios with the greatest financial stakes, particularly those participating in regional and national competition circuits that require new costumes for each routine every season.
The buy-and-resell cycle offers a financially intelligent model: purchase a quality costume secondhand at season start, maintain it through performances, and resell at comparable price at season end. Net costume cost can approach zero when executed with care. This strategy works best for competition pieces with short performance lifecycles but high initial retail prices.
What This Means for Studio Operators
Editorial analysis, not reported fact:
Costume sourcing deserves the same strategic rigor applied to pricing tuition, managing payroll ratios, and optimizing class schedules. Studios operating near break-even on tuition revenue cannot afford to treat costumes as a pass-through expense. The $25 to $30 labor markup is not optional; it reflects real administrative costs that must be recovered to maintain healthy margins.
Multi-vendor strategies require upfront effort but deliver measurable risk reduction and cost control. Establishing relationships with both catalog suppliers for volume orders and specialty vendors for signature pieces creates flexibility when production delays or price increases occur. October ordering for spring recitals should become a non-negotiable calendar milestone, enforced through parent communications and registration deadlines.
The resale channel merits serious consideration, particularly for studios with competitive teams. Facilitating a consignment system or partnering with resale platforms creates value for families while positioning the studio as budget-conscious. Costume doubling and parent involvement demonstrate similar awareness of family economics, which directly impacts retention economics and pricing perception.
Finally, transparent markup communication prevents price resistance. When parents understand that costume fees include measurement, inspection, sorting, and return management, the $75 to $100 per-costume charge becomes defensible rather than arbitrary. Studios that articulate their cost structure build trust and reduce friction around what is often the second-largest family expense after tuition.
Sources & Further Reading
- Dance Teacher: Ask the Experts – How Much Profit Do You Make From Recital Costumes?, analysis of studio costume economics and profit margins
- Dance Studio Owners Association: Costuming, industry benchmarks on labor costs and parent pricing
- Jackrabbit Dance: Budget-Friendly Costumes, cost-saving tactics including handmade options and parent involvement
- Dance Studio Manager: Dance Costume Companies, vendor landscape overview and partnership options
- Buy Sell Dance: Why Dancers Are Choosing Resale Over Retail in 2026, resale market trends and buy-and-resell economics
- Dance Informa: Dance Costume Liquidation Sale, clearance event opportunities and discount timing
- City Dance: Top Dance Costume Companies in the World, wholesale providers and product range comparison
Editorial coverage of publicly reported industry developments. Dance Studio Journal has no commercial relationship with any companies named.